What Is Cash-and-Carry Arbitrage in Crypto?
Cash-and-carry arbitrage is a crypto trading strategy that attempts to profit from the price difference between a cryptocurrency in the spot market and its futures contract.
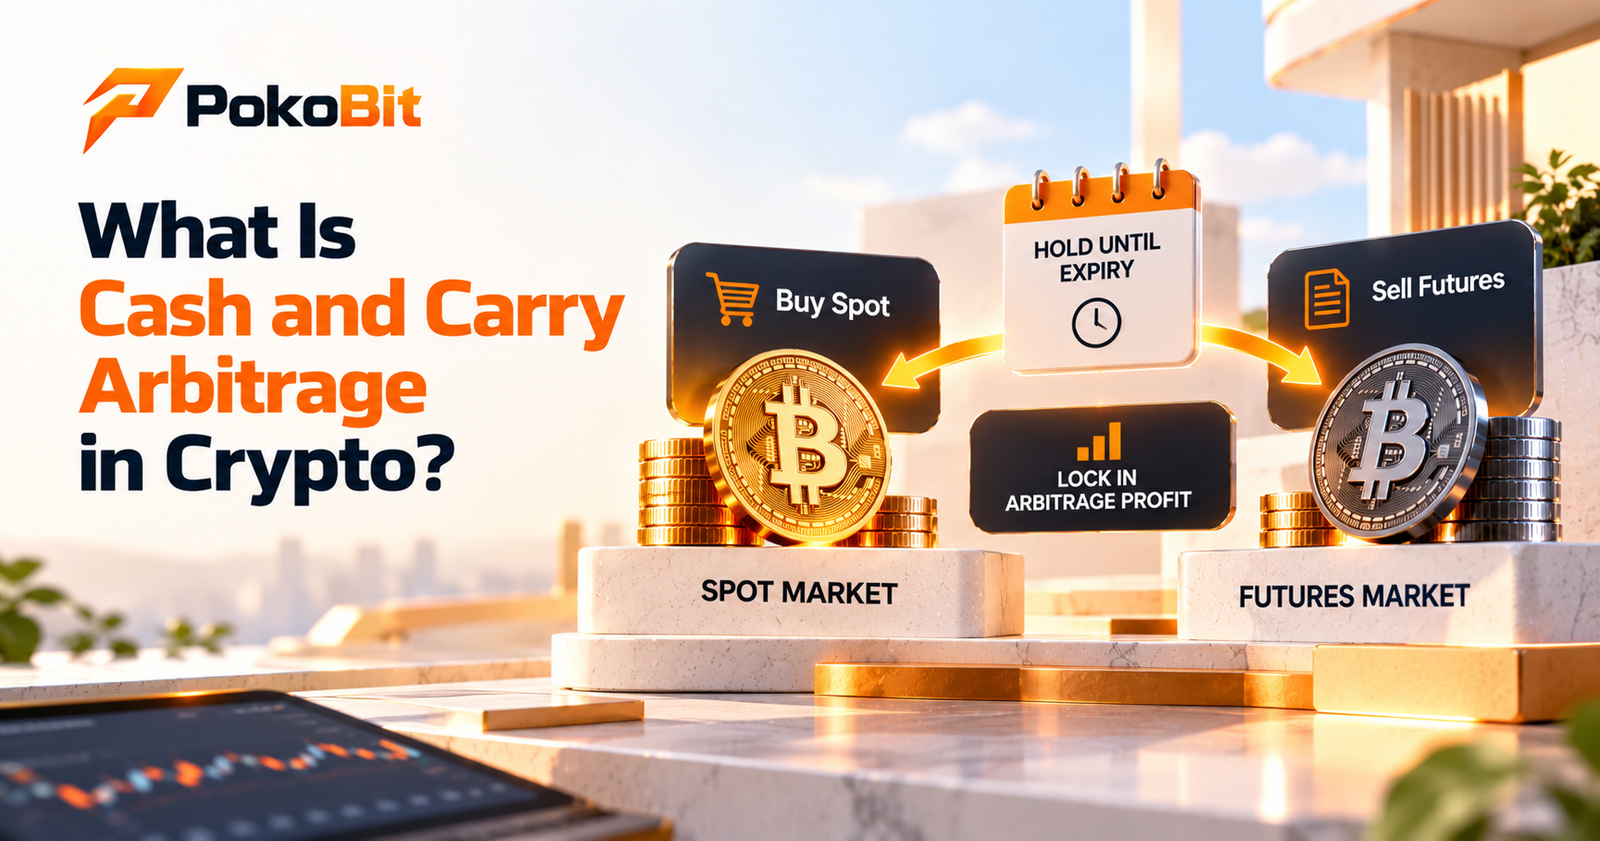
The basic strategy involves buying the cryptocurrency in the spot market while simultaneously taking a short position on a related futures contract.
The trader is not primarily trying to predict whether Bitcoin, Ethereum or another cryptocurrency will rise or fall. Instead, the objective is to capture the difference between the spot price and futures price as the two markets move closer together or as the futures contract approaches settlement.
Cash-and-carry arbitrage is therefore closely related to spot-futures arbitrage.
For a broader explanation of the underlying strategy, see What Is Spot-Futures Arbitrage?.
How Does Cash-and-Carry Arbitrage Work?
The strategy has two main positions:
- Buy the cryptocurrency in the spot market.
- Short the corresponding futures contract.
Suppose Bitcoin is trading at:
Spot BTC price: $100,000
Bitcoin futures price: $103,000
The futures contract is trading $3,000 above the spot price.
A trader could potentially buy Bitcoin for $100,000 in the spot market while shorting the futures contract at $103,000.
If the futures price eventually converges toward the spot price, the trader may be able to capture part of the original difference.
The actual result depends on the contract specifications, execution prices, fees, liquidity and other costs.
Why Is It Called Cash-and-Carry?
The name comes from the traditional structure of the strategy.
"Cash" refers to purchasing the underlying asset in the spot market.
"Carry" refers to holding that asset while maintaining the corresponding futures position.
In traditional financial markets, carrying the underlying asset can involve financing, storage, insurance and other costs.
In crypto, the costs can be different and may include trading fees, custody costs, network fees, borrowing costs and other expenses.
A Simple Example
Consider this illustrative example:
Bitcoin spot price: $100,000
Bitcoin futures price: $103,000
Suppose a trader buys one Bitcoin in the spot market for $100,000.
At the same time, the trader shorts one Bitcoin futures contract at $103,000.
The initial futures premium is:
$103,000 − $100,000 = $3,000
If the futures contract later settles at $100,000, the short futures position gains approximately $3,000 before fees and other costs.
The spot Bitcoin is still worth approximately $100,000.
The combined strategy could therefore capture the original futures premium, subject to the specific settlement mechanism and all associated costs.
This is a simplified illustration rather than a guaranteed return.
What Is the Futures Basis?
The difference between the futures price and the spot price is commonly referred to as the basis.
A simple calculation is:
Basis = Futures Price − Spot Price
Using the example above:
$103,000 − $100,000 = $3,000
The percentage basis is:
($103,000 − $100,000) ÷ $100,000 × 100 = 3%
So the futures contract has a 3% premium over the spot market in this example.
However, a 3% basis does not automatically mean a trader can earn 3%.
Trading fees, slippage, financing costs, funding payments and the time required to hold the position all affect the actual return.
What Happens When the Futures Contract Converges?
One of the important characteristics of cash-and-carry arbitrage is futures convergence.
As a dated futures contract approaches its settlement date, its price generally converges toward the underlying asset's settlement value according to the contract's rules.
If the trader entered the position when futures were trading above spot, the short futures position can potentially benefit from the reduction in that premium.
For example:
Initial spot price: $100,000
Initial futures price: $103,000
Initial basis: $3,000
Later futures price: $101,000
Spot price: $100,000
Remaining basis: $1,000
The futures premium has narrowed from $3,000 to $1,000.
The short futures position has benefited from that reduction in the futures price relative to the entry price.
Cash-and-Carry vs Reverse Cash-and-Carry
Cash-and-carry is normally associated with buying the underlying asset and shorting the futures contract when futures trade above spot.
Reverse cash-and-carry uses the opposite structure.
A trader may:
- Short or otherwise obtain a short exposure to the spot asset.
- Go long the futures contract.
This can potentially be considered when futures trade below the spot market.
However, the reverse strategy can be more complicated in crypto because obtaining a spot short position may require borrowing the asset or using another suitable instrument.
The availability and cost of borrowing therefore matter.
Cash-and-Carry Arbitrage vs Funding Rate Arbitrage
These strategies are related but should not be treated as identical.
Cash-and-carry arbitrage traditionally focuses on the difference between spot and dated futures prices.
Funding rate arbitrage generally focuses on perpetual futures and the recurring funding payments exchanged between long and short positions.
For example:
Cash-and-carry:
Buy spot + short dated futures.
Funding rate arbitrage:
Buy spot + short perpetual futures when the funding environment is favorable.
Perpetual futures do not have a traditional expiry date, so funding payments become an important part of their pricing mechanism.
For more information, see How Does Funding Rate Arbitrage Work?.
What About Perpetual Futures?
The term cash-and-carry is most commonly associated with dated futures because the strategy can be structured around the futures contract's convergence toward settlement.
Perpetual futures work differently because they generally have no expiry.
Instead, funding payments help keep the perpetual contract's price connected to the underlying market.
A spot-plus-perpetual short position can therefore resemble cash-and-carry economically, but its potential return may come from funding payments rather than a fixed futures premium converging at expiry.
This distinction is important when calculating expected returns.
How Do You Calculate Cash-and-Carry Returns?
A simplified calculation starts with the futures premium.
Suppose:
Spot price: $100,000
Futures price: $103,000
Gross basis: $3,000
Gross basis percentage:
$3,000 ÷ $100,000 × 100 = 3%
The next step is to subtract the relevant costs.
A simplified net-return calculation could be:
Net Return = Futures Basis − Trading Fees − Slippage − Financing Costs − Other Applicable Costs
For example, if the gross basis is $3,000 and total estimated costs are $600:
$3,000 − $600 = $2,400
The estimated net return would be $2,400 before considering other factors that could affect the trade.
Why the Annualized Return Matters
A 3% basis does not tell you enough by itself.
You also need to know how long the capital must remain committed.
For example, suppose:
Expected net return: 3%
Holding period: 90 days
A simple annualized approximation would be:
3% × (365 ÷ 90) ≈ 12.17%
This is only a simple annualization and should not be interpreted as a guaranteed annual return.
A 3% opportunity held for 30 days has very different capital efficiency from a 3% opportunity requiring a full year.
What Are the Main Risks?
Cash-and-carry arbitrage can reduce directional exposure, but it does not eliminate risk.
Basis Risk
The futures and spot markets may not behave exactly as expected.
The basis can widen before it narrows, which can affect margin requirements and the trader's ability to maintain the position.
Execution Risk
The spot purchase and futures short may not execute at the prices originally observed.
Fast markets can cause slippage between the two orders.
Liquidity Risk
A displayed futures premium may not be available for the full position size.
Order-book depth must be considered before assuming that the entire spread can be captured.
Margin Risk
Futures positions require margin.
Even when the spot position is intended to hedge the futures position, insufficient margin can create liquidation or forced-position-management risks.
Financing Costs
If the strategy requires borrowing capital or the underlying asset, borrowing costs can reduce the potential return.
Exchange Risk
The strategy may depend on one or more exchanges.
Technical outages, withdrawal restrictions, API failures or other operational issues can interfere with execution.
Settlement Risk
Dated futures have specific settlement rules.
The trader needs to understand the contract's settlement price, expiry time and settlement mechanism before entering the strategy.
Why Fees Matter
Cash-and-carry arbitrage involves at least two sides of the trade.
The trader must consider the cost of entering and exiting both the spot and futures positions.
For example:
Spot entry fee
Futures entry fee
Spot exit fee
Futures exit fee
Slippage
Transfer or network costs where applicable
Borrowing or financing costs where applicable
A large displayed basis can become much less attractive after these costs are included.
This is why arbitrage analysis should focus on the expected net opportunity rather than the headline spread.
Can Cash-and-Carry Arbitrage Be Automated?
Yes.
An automated system can monitor spot and futures markets continuously and calculate the difference between them.
A scanner can potentially track:
- Spot prices
- Futures prices
- Basis percentage
- Contract expiry
- Funding rates where applicable
- Trading fees
- Liquidity
- Estimated slippage
- Margin requirements
- Expected net return
The system can then rank opportunities based on predefined criteria.
For traders researching automated crypto arbitrage, PokoBit focuses on identifying arbitrage opportunities across cryptocurrency markets.
Automation can make monitoring faster, but it does not eliminate execution or market risk.
Cash-and-Carry Arbitrage Workflow
A practical workflow is:
- Select a cryptocurrency and suitable futures contract.
- Check the current spot price.
- Check the futures price.
- Calculate the basis.
- Determine the futures expiry and settlement rules.
- Estimate trading fees.
- Estimate slippage.
- Consider financing or borrowing costs.
- Calculate the expected net return.
- Compare the return with the capital and margin required.
- Enter the spot and futures positions according to the strategy.
- Monitor both positions until the planned exit or settlement.
The key is to evaluate the entire trade rather than focusing on the futures premium alone.
Conclusion
Cash-and-carry arbitrage is a strategy that attempts to capture the price difference between a cryptocurrency in the spot market and a related futures contract.
The classic structure involves buying the underlying asset while shorting the futures contract. If the futures premium narrows or converges toward the underlying price, the trader may capture part of that difference.
However, the displayed basis is not the same as guaranteed profit. Trading fees, slippage, financing costs, liquidity, margin requirements and settlement rules all affect the final result.
For beginners, the most important concept is simple: cash-and-carry arbitrage is about the relationship between spot and futures prices, not about predicting whether the cryptocurrency itself will rise or fall.
SEO Publishing Details
SEO Title:
Slug:
Excerpt:
Meta Title:
Meta Description:
Meta Keywords:
Canonical URL:
Category: Arbitrage Strategies